- Know Exactly What You Have
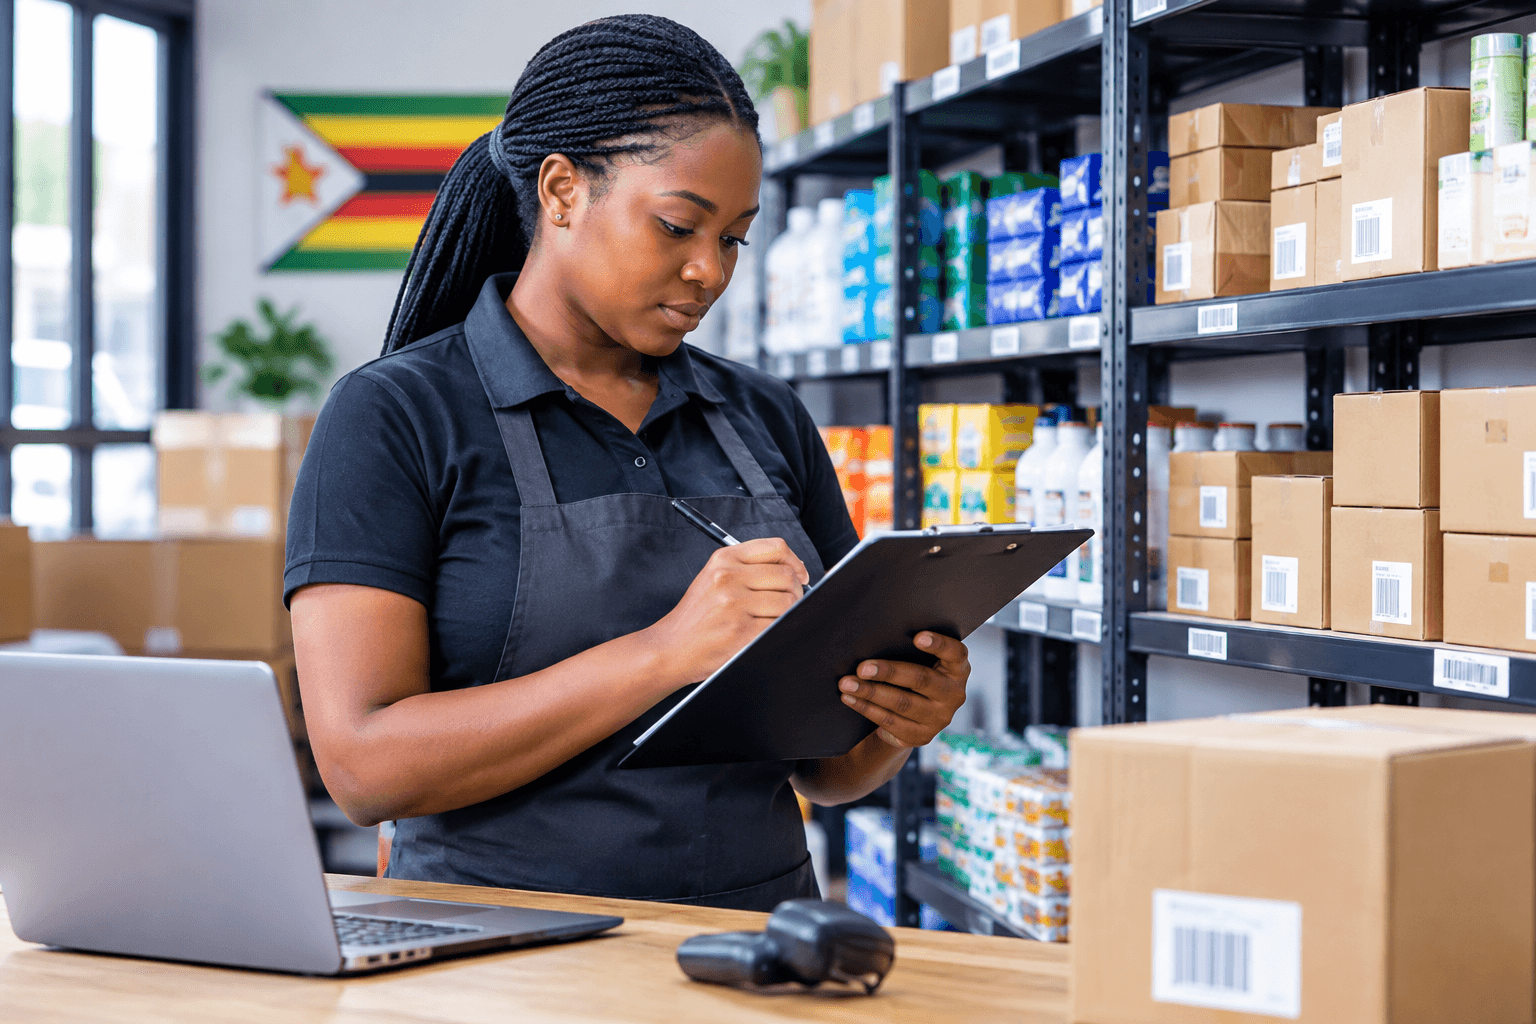
Start with a reliable stock list. Each product should have a clear description, unit of measure and, where useful, a stock code or barcode. If the business sells similar products with different sizes, brands or prices, avoid vague descriptions that make accurate counting difficult.
Regular physical counts should then be compared with the accounting or inventory system. The purpose is not just to find a shortage; it is to identify patterns.
- Investigate Stock Differences — Don’t Just Adjust Them
When the system says there should be 50 units but only 44 are on the shelf, do not simply change the system to 44 and move on. Ask what caused the six-unit difference. It could be an unrecorded sale, damaged stock, theft, a receiving error, a counting mistake or goods issued to another location.
A simple stock-loss log can record the item, quantity, date, estimated value, reason and person responsible for reviewing the difference.
- Tighten Receiving Procedures
Stock control starts before the goods reach the shelf. When a delivery arrives, compare the supplier invoice or delivery note with what was actually received. Check quantities, product descriptions and visible damage before the delivery is accepted.
This is especially important when a business receives high-value stock or large deliveries. An error at receiving can become difficult to trace once the goods have been mixed with existing inventory.
- Separate Stock Duties Where Possible
Where the size of the business allows, avoid giving one person complete control over ordering, receiving, recording and issuing stock. Simple separation of duties creates an additional check and makes unexplained losses easier to investigate.
For a small business with only a few employees, full separation may not be practical. In that case, the owner or manager can perform regular independent spot checks.
- Watch for Theft Without Creating a Hostile Workplace
Stock theft is only one possible cause of losses, but it should not be ignored. High-value, small-sized and easily resold items deserve particular attention.
Use sensible controls such as restricted stockroom access, documented stock issues, point-of-sale controls and regular spot counts. The goal is to create a system where transactions are visible and accountable rather than relying only on trust.
- Deal With Damaged, Expired and Slow-Moving Stock
Not every stock loss is caused by theft. Products can lose value because they expire, become damaged, become obsolete or simply stop selling.
Use the right stock rotation method for the type of goods you sell. For products with expiry dates, a first-expiry-first-out approach can help reduce avoidable wastage. Review slow-moving items regularly and decide whether to discount, bundle, return or stop ordering them where commercially appropriate.
- Watch Stock at Multiple Locations
If your business has a shop, storeroom, warehouse, vehicle or second branch, stock can move between locations without being properly recorded. Every transfer should have a simple record showing what moved, when it moved, where it went and who authorised it.
- Make Stock Part of Your Monthly Financial Review
Stock losses should not be treated as a warehouse problem only. They affect gross profit, cash flow and the value of assets shown in the business accounts.
Compare stock levels and stock losses with sales each month. If sales are growing but gross margins are falling, investigate whether purchasing costs, pricing, wastage, theft or stock-recording problems are contributing to the difference.
A Simple Stock-Control Routine for Zimbabwean SMEs
- Record every stock receipt before goods are put into normal storage.
- Record every sale, issue, return and internal transfer.
- Investigate differences instead of simply correcting the system balance
- Perform regular physical counts, with spot checks on high-risk items.
- Keep damaged, expired and returned goods clearly identified
- Review slow-moving stock before ordering more.
- Compare stock records with accounting records regularly.
Final Thoughts
Reducing stock losses is less about watching employees and more about building a system that makes mistakes, waste and unexplained movements visible. For a Zimbabwean SME, even a basic stock-control process can protect cash, improve gross margins and prevent small losses from becoming a permanent cost of doing business.
If your stock differences are large, recurring or difficult to explain, consider having your accounting and inventory controls reviewed by a qualified accountant or business adviser.